You’ve probably heard the debate a thousand times. Is Bitcoin going to replace the dollar? Or is it just a speculative bubble waiting to burst? It’s a question that keeps financial analysts up at night and crypto enthusiasts arguing in online forums. But here’s the thing: comparing these two isn’t just about picking a winner. It’s about understanding how money actually works in 2026.
At its core, the difference between Fiat Currency and Digital Currency comes down to who controls the supply and how transactions are verified. One relies on government decree; the other relies on code. If you’re trying to figure out where to park your savings or how to send money abroad without getting hit by massive fees, you need to grasp these mechanics. Let’s break down exactly what separates them, why it matters for your wallet, and which one might fit your needs right now.
The Core Difference: Trust vs. Code
Think of Fiat Currency, like the US Dollar or the Euro, as a promise backed by a government. When you hold a $10 bill, you trust that the Federal Reserve won’t let that note become worthless overnight. This system, known as "full faith and credit," has been the global standard since the 1970s when we abandoned the gold standard. The value isn’t intrinsic; it’s social. We all agree it’s worth something because the law says it is legal tender.
Digital Currency, specifically cryptocurrencies like Bitcoin or Ethereum, flips this model on its head. There’s no CEO, no president, and no central bank managing the supply. Instead, trust is placed in mathematics and cryptography. The security of the network depends on consensus mechanisms like Proof-of-Work (PoW) or Proof-of-Stake (PoS). You don’t need to trust a bank manager; you just need to trust the code. This shift from institutional trust to algorithmic trust is the single biggest philosophical divide between the two systems.
Who Controls the Supply?
This is where things get spicy for economists. Central banks, such as the European Central Bank or the Federal Reserve, have the power to print more fiat money whenever they see fit. They do this to manage inflation, stimulate the economy during recessions, or pay off national debts. While this flexibility helps stabilize economies, it also leads to inflation. Remember Zimbabwe in 2015? Hyperinflation made their currency so worthless that a hundred-trillion-dollar note was worth less than 40 cents. That’s the risk of unlimited supply.
Cryptocurrencies usually operate on fixed supply schedules. Take Bitcoin: there will never be more than 21 million coins. This scarcity is programmed into the protocol. No politician can wake up one morning and decide to double the supply of Bitcoin to fund a new infrastructure project. This predictable issuance rate makes digital currencies attractive as a hedge against inflation, often dubbed "digital gold." However, this rigidity can be a downside during economic crises when governments typically inject liquidity to keep markets moving.
Transaction Speed and Cost
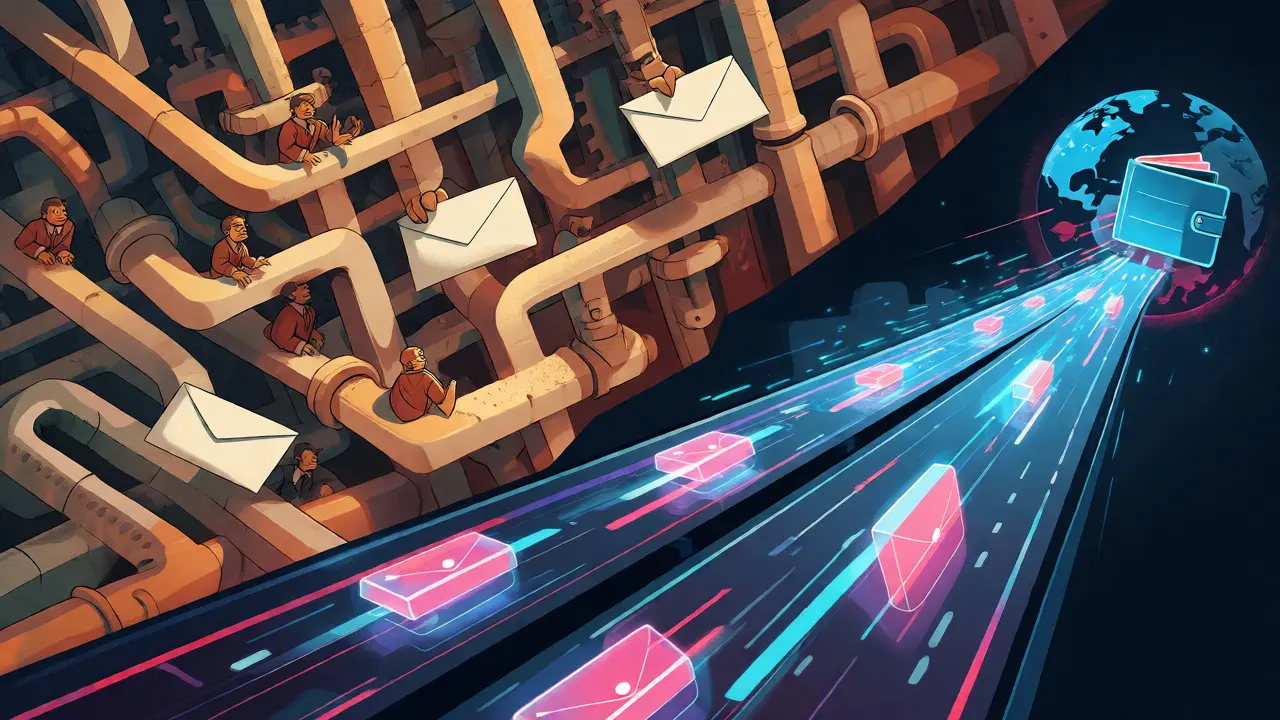
If you’ve ever tried to wire money internationally, you know the pain. Traditional banking systems rely on intermediaries-SWIFT codes, correspondent banks, clearinghouses. A transfer from New York to London can take three to five business days. Why? Because each intermediary needs to verify the transaction and take their cut. Domestic card payments are faster, but merchants still pay fees ranging from 1.5% to 3% per transaction.
Digital currencies aim to cut out the middleman. Using peer-to-peer networks, you can send value directly from your wallet to someone else’s anywhere in the world. Settlement times vary by network. Bitcoin blocks confirm roughly every 10 minutes, while newer chains like Solana or Layer-2 solutions on Ethereum can process transactions in seconds. Fees fluctuate based on network congestion. During peak times, sending a small amount of ETH might cost more in gas fees than the transfer itself, but generally, cross-border crypto transfers remain cheaper and faster than traditional wire services like Western Union.
Privacy and Transparency
There’s a common misconception that crypto is completely anonymous. It’s not. It’s pseudonymous. When you use a debit card, your name, address, and purchase history are linked to the transaction in the bank’s database. With cryptocurrency, your identity is hidden behind a string of alphanumeric characters called a wallet address. However, because blockchains are public ledgers, anyone can trace the flow of funds. If you link your real identity to your wallet (like when you buy crypto on an exchange), your entire financial history on-chain becomes visible to sophisticated analysts.
Fiat transactions offer less privacy but more recourse. If someone steals your credit card number, you can dispute the charge. Banks have fraud protection laws. In the crypto world, if you lose your private key or send funds to the wrong address, that money is gone forever. There’s no customer support hotline to reverse the transaction. This immutability is a feature, not a bug-it ensures censorship resistance-but it demands higher personal responsibility from users.
Volatility and Stability
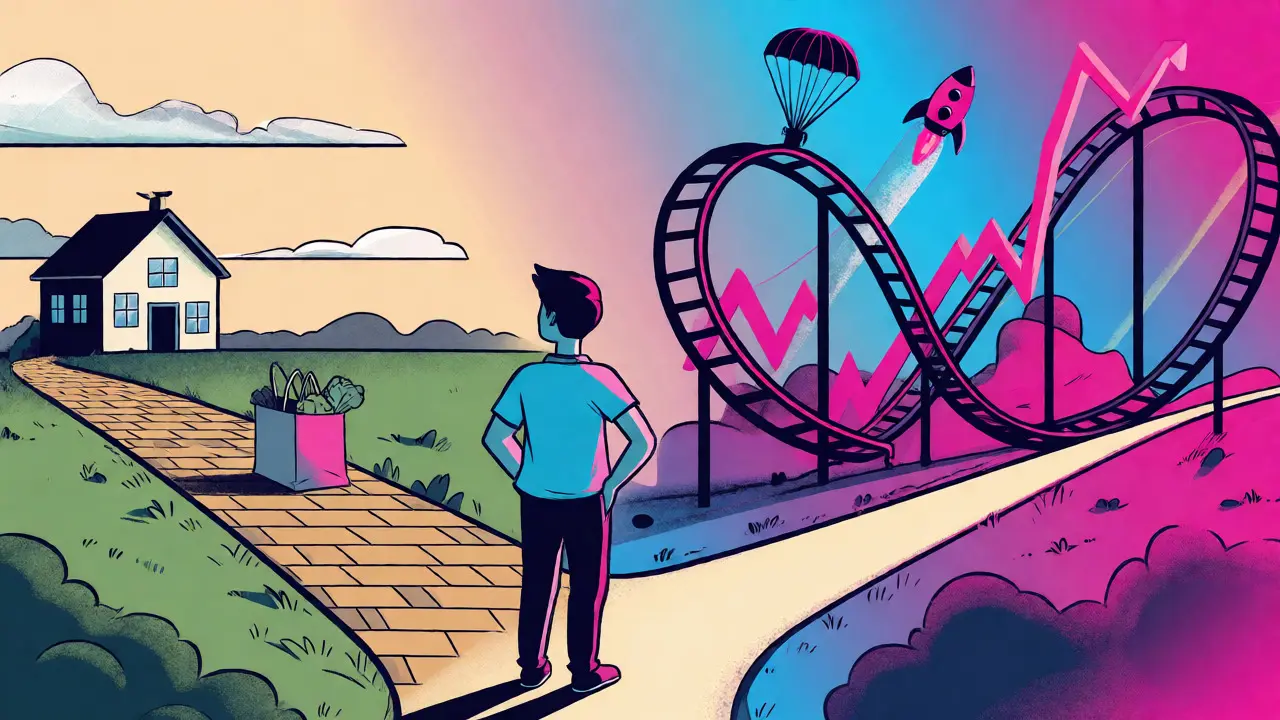
Let’s talk about price stability. For everyday commerce, you need to know that the coffee you bought today costs roughly the same tomorrow. Fiat currencies provide this predictability. Central banks actively manage interest rates to keep inflation around 2%. Cryptocurrencies, however, are notoriously volatile. Bitcoin’s price can swing 10% in a single day based on news headlines, regulatory rumors, or macroeconomic trends.
This volatility makes using digital currency for daily purchases tricky. Would you want to pay rent in a currency that might drop 20% in value before the landlord cashes the check? Most people prefer to hold stablecoins-digital tokens pegged 1:1 to fiat currencies-to bridge this gap. Stablecoins offer the speed of blockchain with the stability of fiat, creating a hybrid tool that many businesses are starting to adopt for payroll and international settlements.
Regulation and Legal Status
The legal landscape is shifting rapidly. As of 2026, most major economies have established frameworks for digital assets. The EU’s Markets in Crypto-Assets (MiCA) regulation provides clear rules for issuers and exchanges. In the United States, agencies like the SEC and CFTC continue to clarify whether specific tokens are securities or commodities. Fiat currency, by contrast, has centuries of legal precedent. Tax laws, property rights, and contract enforcement are well-defined for dollars and euros.
For businesses, accepting fiat is straightforward. Accepting crypto requires accounting for tax implications, potential volatility losses, and compliance with anti-money laundering (AML) checks. While regulatory clarity is improving, uncertainty remains a barrier to mass adoption. Many corporations hesitate to hold significant crypto reserves on their balance sheets due to this unpredictability.
| Feature | Fiat Currency (e.g., USD) | Digital Currency (e.g., BTC) |
|---|---|---|
| Control | Centralized (Government/Central Bank) | Decentralized (Network Consensus) |
| Supply | Unlimited (Managed by Policy) | Limited/Fixed (Programmed Cap) |
| Transaction Speed | Seconds (Domestic) to Days (International) | Minutes to Seconds (Depends on Network) |
| Intermediaries | Banks, Clearinghouses, Payment Processors | Miners/Validators, Nodes |
| Reversibility | Reversible via Dispute Resolution | Irreversible (Immutable Ledger) |
| Physical Form | Bills and Coins exist | Purely Digital |
Which One Should You Use?
So, should you dump your savings into Bitcoin? Probably not entirely. The future likely holds coexistence rather than replacement. Fiat currency remains superior for everyday spending, paying taxes, and short-term financial planning due to its stability and universal acceptance. Digital currencies excel as long-term stores of value, tools for cross-border remittances, and infrastructure for decentralized finance (DeFi) applications.
Consider a diversified approach. Keep your emergency fund in fiat or high-yield savings accounts for immediate access and stability. Allocate a portion of your portfolio to digital assets if you believe in the long-term growth of blockchain technology. Use stablecoins for international transfers to save on fees. Understanding the strengths and weaknesses of both systems allows you to leverage them effectively rather than choosing sides blindly.
Is digital currency safer than fiat currency?
It depends on the type of risk. Fiat currency is protected by government insurance (like FDIC in the US) and legal recourse for fraud. Digital currency is secured by cryptography, making it resistant to counterfeiting, but it carries risks related to user error (lost keys) and market volatility. Neither is inherently "safer"; they protect against different threats.
Can I buy groceries with digital currency?
Yes, but acceptance varies. Major retailers like Microsoft and PayPal allow crypto payments, but local grocery stores may not. Volatility is a barrier, as prices change rapidly. Many users convert crypto to stablecoins or fiat at the point of sale to mitigate this issue.
What happens if the internet goes down?
Digital currencies require internet connectivity to broadcast transactions. If the grid fails, you cannot easily spend crypto. Fiat currency, particularly physical cash, works offline. This resilience makes cash valuable during natural disasters or infrastructure failures.
Are Central Bank Digital Currencies (CBDCs) the same as crypto?
No. CBDCs are digital versions of fiat currency issued by central banks. They are centralized and regulated, unlike decentralized cryptocurrencies. CBDCs aim to combine the efficiency of digital payments with the stability and control of traditional money.
Why is Bitcoin limited to 21 million coins?
This limit is hardcoded into Bitcoin's protocol to create scarcity. Unlike fiat money, which can be printed indefinitely, Bitcoin's fixed supply is designed to prevent inflation caused by monetary expansion, mimicking properties of precious metals like gold.
Anshu Raj
they just want to track every cent we spend and control the flow of money through code that nobody really understands
Mark Regan
Oh, look at us, pretending this is a nuanced debate when it’s clearly not. The article dances around the point like a politician avoiding taxes. Fiat isn't just "social trust," it's institutionalized theft with extra steps. And don’t get me started on the "code" argument; who wrote the code? Who updates it? Who gets rich from the transaction fees while you sit there trusting your precious algorithms? It’s all a rigged game, plain and simple.
You think sending money abroad is faster? Try explaining to your grandmother why her pension check bounced because some validator node in Kazakhstan went offline for maintenance. The frictionless utopia promised by crypto bros never actually materializes for the average person trying to buy groceries or pay rent. We are trading one set of middlemen for another, except now the new middlemen wear hoodies and charge gas fees that fluctuate based on how many people are buying meme coins at 3 AM.
The volatility section is laughably understated. Calling a 10% swing "tricky" is like calling a hurricane "breezy." You can’t plan a life around an asset class that reacts to Elon Musk’s tweets more than actual economic fundamentals. And let’s be real about regulation-it’s not shifting rapidly; it’s being weaponized by central banks who are terrified of losing their monopoly on printing press power. This isn't coexistence; it’s a hostile takeover attempt by legacy institutions using regulatory chokeholds to strangle innovation before it gains traction.
jackie hernandez
OMG YES!!! 🇺🇸💵 America needs to wake up!! We invented the dollar and we should keep it strong without letting these weird internet coins mess things up!! 😤👊 I hate when people say fiat is bad... it works!! My mom uses it every day and she doesn't lose sleep over some random guy on Twitter changing the price of Bitcoin!! 📉📈 Don't let them fool you with the tech talk... it's just a bubble waiting to pop!! 💥🚫 Keep our dollars safe!! ❤️🦅
Fiona C
While the narrative presented here attempts to balance the scales between centralized fiat infrastructure and decentralized cryptographic ledgers, it fundamentally fails to address the systemic fragility inherent in permissionless networks. The assumption that algorithmic consensus provides superior security ignores the attack vectors present in 51% attacks and the environmental externalities of Proof-of-Work mechanisms which remain economically inefficient compared to modern high-throughput payment rails. Furthermore, the comparison of transaction costs is misleadingly simplified; while base-layer settlement may appear cheaper, the off-ramping costs into fiat currency introduce significant slippage and liquidity risks that negate any perceived savings for end-users. Regulatory arbitrage is no longer a viable strategy as global jurisdictions converge on stricter KYC/AML frameworks, effectively eroding the pseudonymity advantage cited in the text. Until digital assets demonstrate consistent low-volatility utility beyond speculative accumulation, they will remain a niche asset class rather than a medium of exchange capable of displacing sovereign legal tender.
Ellie Probus
I am absolutely SHAKING reading this!! 😱 How can you even compare the glorious stability of the US Dollar to this chaotic mess?? It’s like comparing a rock-solid fortress to a house made of cards!! 💳✨ We have FDIC insurance!! We have the Federal Reserve!! We have LAW!! 🏛️⚖️ These crypto folks act like they discovered fire but they’re playing with matches in a gasoline factory!! 🔥🧨 If my bank makes a mistake I call them and they fix it!! If I lose my private key I LOSE MY LIFE SAVINGS FOREVER!! 😭💸 That’s not freedom that’s negligence dressed up in fancy words!! I refuse to live in fear of a glitchy server farm deciding if I can eat dinner tonight!! 🍽️🚫 Go back to your boring stable currencies where adults live!! 🙄💅
Johnny Garza
yall talk too much about theory when the real issue is access. half the world doesn't have a bank account but has a smartphone. crypto gives those folks a shot at financial inclusion without needing a credit score or a branch down the street. its messy yeah but its open. dont gatekeep money just cause you got a steady paycheck
Tiffany Dickens
The analysis provided offers a balanced perspective on the structural differences between the two systems. However, it is worth noting that the transition period may be significantly longer than anticipated due to entrenched network effects within the traditional banking sector. Consumers often prioritize convenience and familiarity over theoretical efficiency gains, which suggests that hybrid models utilizing stablecoins may see broader adoption than pure cryptocurrencies in the near term.
Raman Tiwari
This is such a fascinating breakdown!! 😲 I’ve always wondered about the philosophical divide between trust in institutions versus trust in code. It’s truly mind-bending to think that math can replace government decree!! 🧮✨ But honestly, the part about privacy scared me the most. If everything is on a public ledger, does that mean my spending habits are basically open books for anyone with the right tools?? 📖🔍 It feels like we are trading one form of surveillance for another, just with different players involved. I’d love to hear more thoughts on how regular people can protect themselves in this transparent system!! 🛡️🤔
Varsha Bhat
Hello everyone. I found this discussion quite insightful. In India, we are seeing a unique blend of both systems. Many people use UPI (Unified Payments Interface) which is a centralized digital fiat system, yet there is growing interest in crypto among the younger demographic. It seems the cultural context matters a lot. For us, the speed of domestic transfers via UPI is already very efficient, so the argument for crypto speed is less compelling locally. However, for remittances from overseas workers, the cost savings of crypto are indeed significant. It is a complex picture where technology meets local infrastructure realities.
Ankush Goyal
It is morally bankrupt to suggest that individuals should bear the full risk of holding volatile assets when governments have spent decades building safety nets. The article glosses over the ethical implications of unbacked digital tokens creating wealth inequality. Those who bought early reap the rewards while latecomers hold the bag. This is not innovation; it is speculation disguised as progress. We must prioritize systems that serve the collective good rather than enriching a few technocrats.
Dr. Abhishek Upadhyay
let me clarify something important regarding the technical side. the claim that crypto cuts out middlemen is only partially true. yes the blockchain removes the clearinghouse but you still need exchanges wallets and often custodians. these are new middlemen. also the energy consumption of pow networks is a massive hidden cost that fiat systems do not have in the same way. banks run on existing grid infrastructure whereas mining requires dedicated hardware and constant electricity. if you factor in the carbon footprint the cost per transaction changes dramatically. do not ignore the externalities
Mark Regan
Wow, thanks for the lecture, Dr. Upadhyay. Truly enlightening. Next you'll tell me water is wet. 🙄 The point isn't whether miners use electricity; the point is that the current system forces YOU to subsidize their inefficiency through inflation. At least with crypto, the cost is visible upfront in gas fees rather than hidden in the slow devaluation of your life savings. But sure, stick to your comfortable illusion of stability while your purchasing power evaporates year after year. Enjoy your "efficient" fiat system that takes days to settle international trades and charges you 3% for the privilege of moving your own money. I’ll be over here laughing all the way to the decentralized bank. 🏦💸
Drew Lemmy
i appreciate the nuance here. i think we often forget that fiat is also a technology. it’s just an older one. the social contract behind it is fragile too especially in countries with unstable governments. maybe the goal shouldn’t be replacement but complementarity. having options is good for resilience. i’m curious how others feel about cbdc s though since they seem like the middle ground many regulators want
Hailey Phillips
Hi Drew! That is such a thoughtful point. 😊 I completely agree that resilience comes from diversity. Having multiple ways to transact protects us against single points of failure. Regarding CBDCs, I think they are essential for maintaining monetary policy effectiveness in a digital age. They offer the convenience of cash with the traceability needed for law enforcement. It’s a win-win if implemented correctly with user privacy safeguards!! Let’s hope policymakers listen to experts like you!! 👏🌟
Samantha McClafferty
Listen up, team!! 📢 Stop fighting over which coin is better and start looking at YOUR personal financial health!! 💪 Whether you choose fiat or crypto, the key is understanding your risk tolerance. Are you saving for retirement in 30 years?? Then maybe allocate a small percentage to digital assets for growth potential. Are you saving for next month's rent?? Keep it in stable fiat accounts!! 🏠💰 Don't let the hype train derail your basic budgeting principles. Educate yourself, diversify your portfolio, and don't put money into anything you don't understand!! You've got this!! Go make smart moves!! 🚀📈
Manish Pudasaini
The article is grammatically sound but intellectually lazy. It presents a binary choice where none exists. The reality is a spectrum of monetary instruments. Dismissing the complexity of cross-border settlement layers reduces economics to a blog post. Better research is required.
jordan gautreau
it makes you wonder what money really is. is it paper?? is it numbers?? or is it just shared belief?? 🤔 if we all stop believing in the dollar tomorrow does it vanish?? if we all believe in bitcoin does it become real?? it’s kind of wild that value is just a story we all tell ourselves. maybe the future isn’t about choosing one story over another but writing a new one together. peace and vibes to everyone figuring this out ✌️🌌
Edington Vernita
I appreciate the respectful tone in this thread. It is easy to get heated when discussing money, but remembering that everyone has different financial situations helps. Some people need the stability of fiat for immediate expenses, while others have the capacity to weather volatility for long-term gains. Neither group is wrong; they are just operating under different constraints. Let's try to support each other's choices rather than judging them.
Andrew Ellison
yeah pretty solid take overall. just remember that regulations vary wildly by state and country so what works in california might not work in texas or india. stay flexible